In the vast and ever-evolving landscape of digital finance, few technical features have generated as much debate, narrative, and value as Bitcoin’s hard cap of 21 million units. This is neither a marketing slogan nor a secondary detail of the protocol, but the founding economic rule around which Satoshi Nakamoto built, in 2009, the first decentralized monetary network in history. In an era where central banks can expand the monetary base at their own discretion through tools such as quantitative easing, Bitcoin proposes a radically opposite model: a fixed, predictable monetary policy that can be verified by anyone in real time. For a fintech audience, understanding this mechanism in depth means understanding why Bitcoin continues to attract institutional investors, asset managers, regulators, and ordinary savers around the world.
The Mechanism of Programmed Scarcity
Bitcoin’s supply is not governed by a central entity, but by mathematical rules inscribed in the network’s source code. New bitcoins are created exclusively through mining: computers on the network compete to solve a complex cryptographic puzzle, and whoever succeeds first receives a reward in newly issued bitcoin, along with the transaction fees included in that block.
This reward, however, does not remain constant over time. Every 210,000 blocks mined — an interval that corresponds, on average, to approximately four years — the reward is halved in an event known as the halving. The historical sequence, verifiable on any blockchain explorer by examining block heights and their corresponding coinbase transactions, is as follows:
- 50 BTC per block from block 0 (January 2009) to block 209,999;
- 25 BTC from block 210,000 (November 2012) to block 419,999;
- 12.5 BTC from block 420,000 (July 2016) to block 629,999;
- 6.25 BTC from block 630,000 (May 2020) to block 839,999;
- 3.125 BTC from block 840,000 (April 19–20, 2024) onward, until the next halving expected approximately around 2028.
This halving process will continue until the block subsidy reaches zero, at which point no new bitcoin will be issued by the protocol. Based on the average ten-minute block interval, this is projected to occur around the year 2140. From that point on, miners will be compensated exclusively through transaction fees paid by network users.
Mathematically, the idealized emission curve can be described as a geometric series, since each era of 210,000 blocks issues a subsidy that is half of the previous one:
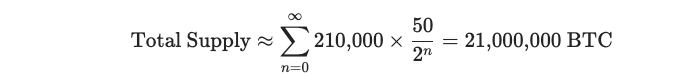
This idealized calculation confirms that the “21 million” figure is the direct mathematical consequence of three parameters embedded in the protocol: an initial subsidy of 50 BTC, a halving interval of 210,000 blocks, and a halving factor of 1/2. It is worth adding a technically precise detail, verifiable directly in the GetBlockSubsidy function of the Bitcoin Core source code: because amounts are handled internally as integers denominated in satoshis and each halving is implemented via integer division that always rounds down, the emission schedule is not truly infinite but terminates after 33 discrete halving eras, once the subsidy is truncated to zero. As a result, the maximum supply actually reachable by the protocol is not exactly 21,000,000 BTC but approximately 20,999,999.9769 BTC — a negligible difference in practical terms, but a technically accurate one.
Why Exactly 21 Million? The Philosophy Behind the Number
The choice of this limit is rooted in a precise ideological vision that took shape in the aftermath of the 2008 financial crisis. During that period, the world’s major central banks expanded their balance sheets in unprecedented ways to prop up banking systems on the verge of collapse, effectively diluting the real value of millions of people’s savings. The 21 million cap represents a deliberate architectural response to this dynamic: a monetary system in which no authority — governmental, banking, or algorithmic — can unilaterally decide to expand the supply in order to solve short-term problems.
This architecture is often described by commentators as consistent with principles associated with the Austrian School of economics, according to which the discretionary manipulation of the money supply is one of the main causes of boom-and-bust cycles. In a fixed-supply system, the value of money cannot be eroded by artificial inflation; it depends exclusively on market demand and on the trust that network participants place in the system.
A Technically Modifiable, but Socially Rigid Limit
One frequently misunderstood aspect concerns the true immutability of this cap. Technically, the value of 21 million is defined in the Bitcoin Core source code and, in principle, could be modified by developers. In practice, however, Bitcoin is a permissionless network based on distributed consensus: every node must voluntarily choose to adopt a new version of the software, and any modification to a fundamental rule such as the maximum supply would require near-unanimous agreement among thousands of independent operators worldwide. The protocol itself also enforces the cap automatically at the technical level: if a miner attempted to assign itself a subsidy higher than what the rules allow at that point in time, every other compliant node on the network would reject that block outright for violating consensus rules. The 21 million limit is therefore, more than an absolute technical constraint, a socially rigid one: the real barrier is not the code itself, but the distributed enforcement mechanism and the collective trust in the scarcity narrative that underpins the entire system.
Measuring Scarcity: The Stock-to-Flow Model
To quantify Bitcoin’s level of scarcity relative to other assets historically considered “hard money,” part of the financial community refers to the Stock-to-Flow (S2F) model, popularized by the pseudonymous analyst PlanB. The model measures the ratio between the existing stock of an asset and its annual flow of new production:
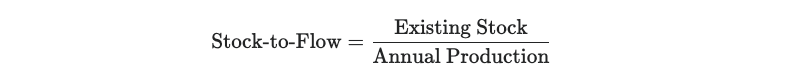
According to commonly cited estimates, gold has an S2F ratio of about 60, and silver sits at around 22. Bitcoin, following the April 2024 halving, had a circulating supply of approximately 19.7 million BTC and an annual new issuance of roughly 164,250 BTC (3.125 BTC per block × 6 blocks per hour × 24 hours × 365 days), yielding a ratio of approximately 120 — a figure that, within the framework of this model, exceeds the S2F ratios typically cited for gold and silver. It is important to note, in the interest of accuracy, that the S2F model remains the subject of extensive debate both within and outside academic circles: numerous analysts contest its predictive power and consider it more a useful comparative indicator of scarcity than an economic law capable of precisely determining the asset’s future price.

Bitcoin vs. Fiat Currencies: Two Monetary Paradigms Compared
The contrast with the traditional monetary system is significant. Fiat currencies generally have no predetermined issuance limit: central banks can expand the monetary base through tools such as quantitative easing, interest rate adjustments, and government bond purchases. Public data from the FRED database of the Federal Reserve Bank of St. Louis show that the balance sheet of the US Federal Reserve grew from approximately $900 billion in 2008 to a peak of nearly $9 trillion (approximately $8.9 trillion) in early 2022.
Bitcoin’s issuance policy, by design, differs on three verifiable technical points:
- Predetermined, since the quantity of BTC that will exist at any future point in time can be calculated today based on the halving schedule encoded in the protocol;
- Transparent, given that the entire issuance history is recorded on the public blockchain and independently verifiable by any node on the network;
- Non-discretionary, since the protocol contains no mechanism allowing any entity to issue bitcoin outside the established subsidy schedule.
Bitcoin’s annualized supply growth rate was significantly higher than that of major fiat currencies in the network’s early years; after successive halvings, this rate has progressively declined and will tend asymptotically toward zero as the protocol approaches its issuance limit around 2140.
Real Scarcity: Lost Bitcoins and Liquid Supply
Not all of the theoretical 21 million bitcoins are, or will be, actually available on the market. According to an analysis published by Chainalysis in 2017, based on the statistical observation of Unspent Transaction Outputs (UTXOs) that had not moved for over a decade, between 2.78 and 3.79 million BTC are estimated to be permanently inaccessible due to lost private keys, damaged hard drives, or owners who died without passing on their access credentials. It is important to emphasize that this is a statistical inference based on publicly available on-chain data, not a cryptographic certainty: it is not possible to distinguish with absolute confidence a genuinely lost private key from one that is simply inactive.
A separate estimate, based on research published in 2013 by Sergio Demian Lerner, identifies approximately 1.1 million BTC linked to Satoshi Nakamoto through the analysis of a specific mining signature present in the network’s earliest blocks, known as the “Patoshi pattern.” These coins have not been moved since 2009 — a fact directly verifiable on-chain — though the attribution to Satoshi remains a strong statistical inference based on mining patterns, not a direct cryptographic proof of ownership. Accounting for both estimates, the effectively accessible supply likely sits somewhere between 17 and 18 million BTC, though the exact figure cannot be established with certainty from blockchain data alone.
Added to this is a further distinction relevant to market participants: the liquid supply, meaning the portion of bitcoin actually available for trading at any given moment, is further reduced by the presence of long-term holders — including HODLers, corporate treasuries, funds, and spot ETFs — who tend to hold the asset for extended time horizons. This means that, in the event of a sudden demand shock, the effect on price can be amplified relative to what the headline total supply figure alone would suggest.
Halving as a Market Catalyst
Over the years, halvings have taken on an almost mythological role in Bitcoin’s market cycles. Historically — with all the caution required when extrapolating patterns from a still relatively young asset, and noting that only four halvings have occurred to date, which does not allow for a demonstrated cause-and-effect relationship — the reduction in the supply of new coins available for purchase has often coincided, in the twelve to eighteen months following each event, with phases of strong price appreciation. For fintech operators, fund managers, and trading platforms, halvings have nonetheless become key moments around which to build communication, investment products, and portfolio rebalancing strategies.
The Debate: Criticisms of Absolute Scarcity
Not everyone agrees that a rigidly fixed supply necessarily represents an advantage. Some economists, including Nobel laureate Paul Krugman, have argued that a currency with a totally inelastic supply is structurally deflationary, and that deflation can be as economically damaging as inflation — if not more so — since it incentivizes consumers to delay purchases in anticipation of lower future prices, thereby slowing the circulation of money and economic growth. Bitcoin’s supporters respond by distinguishing between “demand-driven” deflation, typically associated with recessions, and “supply-driven” or productivity-driven deflation, historically associated with phases of technological progress. They also note that Bitcoin is not designed to fully replace fiat currencies in the short term, but rather to serve as a store of value and a diversification element.
Alongside this criticism stands another, less discussed but equally relevant one: the total absence of any countercyclical monetary lever. Fiat currencies can be managed countercyclically, with central banks expanding the money supply and lowering rates during recessions; Bitcoin, by design, cannot play this role, since its supply is entirely inelastic and there is no entity capable of adapting it to the needs of the economic cycle. Furthermore, a fixed-supply system with a strong “first mover” effect tends, over time, to disproportionately reward early adopters relative to later entrants — a phenomenon acceptable for an investment asset, but potentially problematic if Bitcoin were ever to aspire to the role of a fully-fledged global currency.
What Happens After 2140?
A less frequent, but crucial, question concerns the long-term sustainability of the system: what will happen once the block subsidy reaches zero? From that point on, miners will no longer receive any reward in newly issued coins, and their compensation will depend exclusively on the transaction fees paid by network users. For the network to remain secure, these fees will need to be high enough to offset the energy and infrastructure costs of mining — one of the most widely discussed challenges in Bitcoin’s long-term roadmap, and one for which no settled answer currently exists. Solutions such as the Lightning Network are already being developed in part with this transition in mind, allowing the main blockchain to focus on higher-value transactions with meaningful fees, while everyday micropayments are processed on a more efficient secondary layer.
Yet an open question remains — perhaps more relevant than the technical solidity of the limit itself: will the global community, users, investors, institutions, and regulators, continue to recognize this rule as legitimate and inviolable? If the answer is yes, Bitcoin’s limited supply will remain one of the most fascinating, and potentially most disruptive, monetary experiments of the digital age.
This article is provided for informational purposes only and does not constitute financial, investment or legal advice, nor a recommendation or endorsement of any platform. Crypto-assets are highly volatile and involve a risk of partial or total loss.
Some links in this article may be affiliate links, which means The Fintech Mirror may receive a commission at no additional cost to the reader.